
Land Seller Series — Article 12.1Do I Need a Survey Before I Sell My Land? [Yesterday, finalizing Article 12, I realized the importance of expanding on the subject of the land survey for

Dated: September 23 2026
Views: 14
(8-minute read)
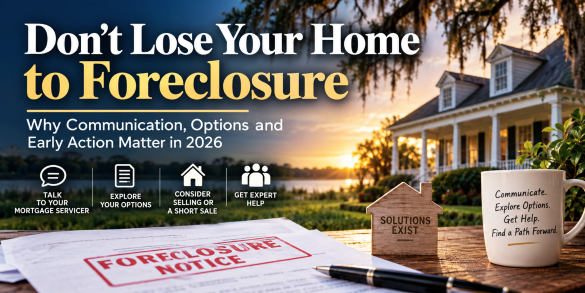
Financial difficulties can happen to almost anyone.
A job loss, reduction in income, unexpected medical expense, divorce, death in the family, natural disaster, rising household expenses—or simply several financial setbacks occurring at once—can turn a manageable mortgage payment into a serious problem.
When that happens, it can be tempting to avoid the situation.
You may stop opening letters. You may hesitate to answer calls from your mortgage company. You may feel embarrassed about being behind and hope that somehow the situation will improve before you have to deal with it.
But when it comes to mortgage trouble, doing nothing can be the worst choice you can make.
The Consumer Financial Protection Bureau (CFPB) currently advises homeowners who cannot make their mortgage payment —or believe they may soon miss one— to contact their mortgage servicer as soon as possible.
That advice reinforces a message that has been around for years: Communication is essential.
Don't Wait Until Foreclosure Is Underway
The original article on which this post is based made an important observation: lenders generally would rather find a workable solution than proceed with foreclosure, but communication with the borrower is necessary to explore alternatives.
That basic principle remains relevant in 2026.
One terminology change is worth noting. The company you need to contact is usually your mortgage servicer. Your lender is the financial institution that originally made your loan; your servicer is the company that handles your account, collects your payments, sends your mortgage statements and works with borrowers on available assistance options. They may or may not be the same company.
If you're having difficulty making your payment, contact the servicer listed on your mortgage statement as early as possible.
You do not have to wait until you have missed several payments.
Earlier communication may leave you with more options.
Be prepared to explain your situation clearly and honestly.
Your servicer may ask why you are having difficulty making the payment, whether the problem appears temporary or long-term, what your current income and expenses are, and what assets or resources you have available.
The CFPB recommends providing this information so the servicer can determine which assistance —or loss-mitigation— options may be available.
You may also be asked to complete a mortgage-assistance application and provide supporting financial documents.
Respond promptly to requests for additional information and keep copies of everything you submit.
Mortgage assistance is not one-size-fits-all.
Depending on your mortgage, financial circumstances and the rules of the investor or government program backing the loan, possible solutions may include:
Not every borrower will qualify for every option, and the financial, tax, credit and legal consequences can differ significantly.
That is why contacting the servicer—and obtaining qualified professional advice when appropriate—is so important.
This is one area where today's housing environment makes it especially important not to assume that foreclosure is inevitable.
If your home's current market value is greater than the mortgage balance and other amounts that must be paid at closing, you may be able to sell the property conventionally, satisfy the mortgage and retain the remaining proceeds.
The CFPB specifically identifies selling as an option homeowners should consider when the property is worth more than the mortgage balance, noting that an ordinary sale is generally better financially and for credit than foreclosure, a short sale, or a deed-in-lieu.
A homeowner who is behind on payments therefore should not assume that being delinquent automatically means losing the home to foreclosure.
One of the first practical questions may be:
What is my home realistically worth today, and how does that compare with everything I owe?
A knowledgeable real estate professional can help estimate current market value and expected selling expenses. Your mortgage servicer or closing professional can provide or help obtain the figures needed to determine the approximate payoff.
That's a different situation—but it still doesn't mean you should simply walk away.
A short sale may sometimes be considered when the property's expected sale proceeds will not be sufficient to satisfy the mortgage and other required obligations.
A short sale requires cooperation and approval from the appropriate mortgage servicer, investor and possibly other lienholders. It is not simply an ordinary sale at a reduced price.
The original article also recognized short sales as a possible way of resolving serious mortgage delinquency rather than allowing the situation to proceed unchecked to foreclosure.
If a short sale is being considered, homeowners should understand the potential consequences—including whether any unpaid balance could remain, how the transaction may affect credit, and whether there may be tax or legal consequences.
Those questions should be addressed by the appropriate mortgage, legal and tax professionals rather than assumed.
There are also protections today that homeowners should know about.
Under federal mortgage-servicing rules, in most circumstances a servicer cannot make the first notice or filing required to begin foreclosure until the borrower is more than 120 days delinquent. Other protections may apply when a borrower submits a complete loss-mitigation application.
That does not mean a homeowner should wait 120 days before seeking assistance.
Quite the opposite.
Those protections are another reason to begin communicating and submitting requested information as early as possible.
You do not necessarily have to navigate this process alone.
A HUD-approved housing counseling agency can help homeowners understand their financial situation, communicate with their mortgage company, evaluate available loss-mitigation options and work through required paperwork.
The CFPB directs struggling homeowners to HUD-approved counselors and notes that foreclosure-prevention assistance is available at no cost. Homeowners can also reach the HOPE™ Hotline at 888-995-HOPE (4673).
CFPB Mortgage Help for Homeowners
HUD FHA Loss-Mitigation Information
Unfortunately, financial distress can make homeowners targets for scammers.
Be particularly cautious if someone:
asks for a large upfront payment to "save" your home, guarantees that your mortgage will be modified, promises that foreclosure definitely will be stopped, tells you to stop communicating with your servicer, instructs you to send your mortgage payment somewhere other than your servicer, or asks you to sign over ownership of your property.
The CFPB specifically warns consumers about these tactics. Legitimate assistance is available directly through mortgage servicers and HUD-approved housing counselors without paying someone thousands of dollars for promises they may not be able to keep.
For Louisiana homeowners, another point deserves emphasis: foreclosure isn't merely a matter between a homeowner and mortgage company. It involves Louisiana law and legal procedures.
Depending on how a foreclosure is conducted and the particular circumstances involved, questions can arise concerning appraisal, judicial sale and whether a creditor may pursue a deficiency judgment for an unpaid balance remaining after the property is sold. Louisiana law specifically addresses when deficiency judgments may be available.
For that reason, a Louisiana homeowner who has received foreclosure papers—or believes a foreclosure sale may be imminent—should consider promptly consulting a Louisiana attorney experienced in foreclosure or consumer law.
A real estate agent can help evaluate the possibility of selling the property, but legal advice should come from an attorney.
Perhaps the most important lesson from the original article is also the simplest.
Don't disappear. Communicate.
The original source observed that borrowers sometimes allowed their homes to move toward foreclosure without first having a meaningful conversation with their lender.
That remains valuable advice in 2026.
If you are having trouble making your mortgage payment:
Contact your mortgage servicer. Ask what options are available. Gather your financial information. Respond promptly to requests for documents. Consider talking with a HUD-approved housing counselor. Determine what your property is worth. And, if necessary, obtain legal and tax advice before making major decisions.
Foreclosure may eventually be unavoidable in some circumstances. But homeowners should not assume that outcome before investigating their alternatives.
Sometimes the solution is keeping the home.
Sometimes the best available path is selling it.
Sometimes a short sale or another loss-mitigation option may be appropriate.
The important thing is to start the conversation early enough to find out.
Source Credit & 2026 Update
This article was inspired by and substantially updated from “Don’t Lose Your Home to Foreclosure,” which reproduced information from Baton Rouge Business Report Online – Real Estate Weekly, by Brian Andrews, Certified Mortgage Banker, Andrews Commercial Mortgage. The original article emphasized communicating with one's lender when facing mortgage delinquency rather than simply allowing a property to proceed into foreclosure.
The 2026 version I have created with assistance from ChatGPT for updating and organization has been independently updated and expanded using current consumer guidance from the Consumer Financial Protection Bureau (CFPB) and U.S. Department of Housing and Urban Development (HUD), together with relevant Louisiana statutory information.
Educational disclaimer: This article provides general real estate and consumer information and is not legal, tax, credit, mortgage, or financial advice. Foreclosure laws and assistance programs can change, and individual circumstances vary. Homeowners facing foreclosure should consult their mortgage servicer and the appropriate qualified professionals regarding their particular circumstances.
Shared by:
Randall C. (Randy) Anderson, REALTOR®/Agent
LOCAL PROFESSIONAL COMMITTED
M o v e R e a l t y , L L C
Licensed in Louisiana Agent License: #58902
2107 S. Burnside Av, Suite #3 Gonzales, LA 70737
Office: 225 644-7797 Mobile: 225 921-9777
Email: RandallAndersonREALTOR@gmail.com
Social media: Instagram; Facebook; Youtube; Linkedin
FREE Search | ALL Area Listings | ANY Time
www.ThatREALTORWithTheBeard.com
OR USE MY MLS MOBILE APP WHILE YOU ARE ON THE GO!!
Millions Mapped App = To install, simply text "randy" to 225-310-6511
My Graphic Blog: https://tinyurl.com/RcAGraphicBlog
Videos - YouTube Channel: http://bit.ly/MoveRealtyRcAVideos
Check Out: Client Testimonials
🔑 YOUR DREAMS | OUR PASSION 🔑

I am a REALTOR®/Agent at Move Realty, I grew up and live in Gonzales, Louisiana. I am married to Eileen (Clyde) Anderson, father to three daughters and a step-son, grandfather to five amazing....
Land Seller Series — Article 12.1Do I Need a Survey Before I Sell My Land? [Yesterday, finalizing Article 12, I realized the importance of expanding on the subject of the land survey for
Don’t Lose Your Home to Foreclosure: If You’re Struggling With Your Mortgage, Start by Communicating(8-minute read)Financial difficulties can happen to almost anyone.A job loss,
Land Seller Series — Article 12What Documents Do I Need to Sell My Land? (14-minute read)Selling land can seem pretty simple: find a buyer, agree on a price, sign the paperwork, and get
What Not to Overlook on Your Final Walk-Through(8-minute read)The final walk-through is one of the last opportunities a homebuyer has to look carefully at a property before completing the purchase.
 The multiple listing information is provided by the Greater Baton Rouge Association of REALTORS®, Inc. multiple listing service from a copyrighted compilation of listings. The compilation of listings and each individual listing are ©2026 MLS. All Rights Reserved. The information provided is for clients' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties clients may be interested in purchasing. All properties are subject to prior sale
or withdrawal.
Show More...
